The Scored Applicant
Germany's financial regulator BaFin will begin overseeing how banks and insurers use artificial intelligence after lawmakers expanded its powers, Reuters reported on July 29th. The watchdog will monitor customer-facing chatbots, systems that assess creditworthiness, and practices that collect or analyze sensitive information. It will also be able to impose fines when AI disadvantages people or blocks fair access to financial services. A bank's automated judgment now arrives with a regulator assigned to inspect the machinery behind it.
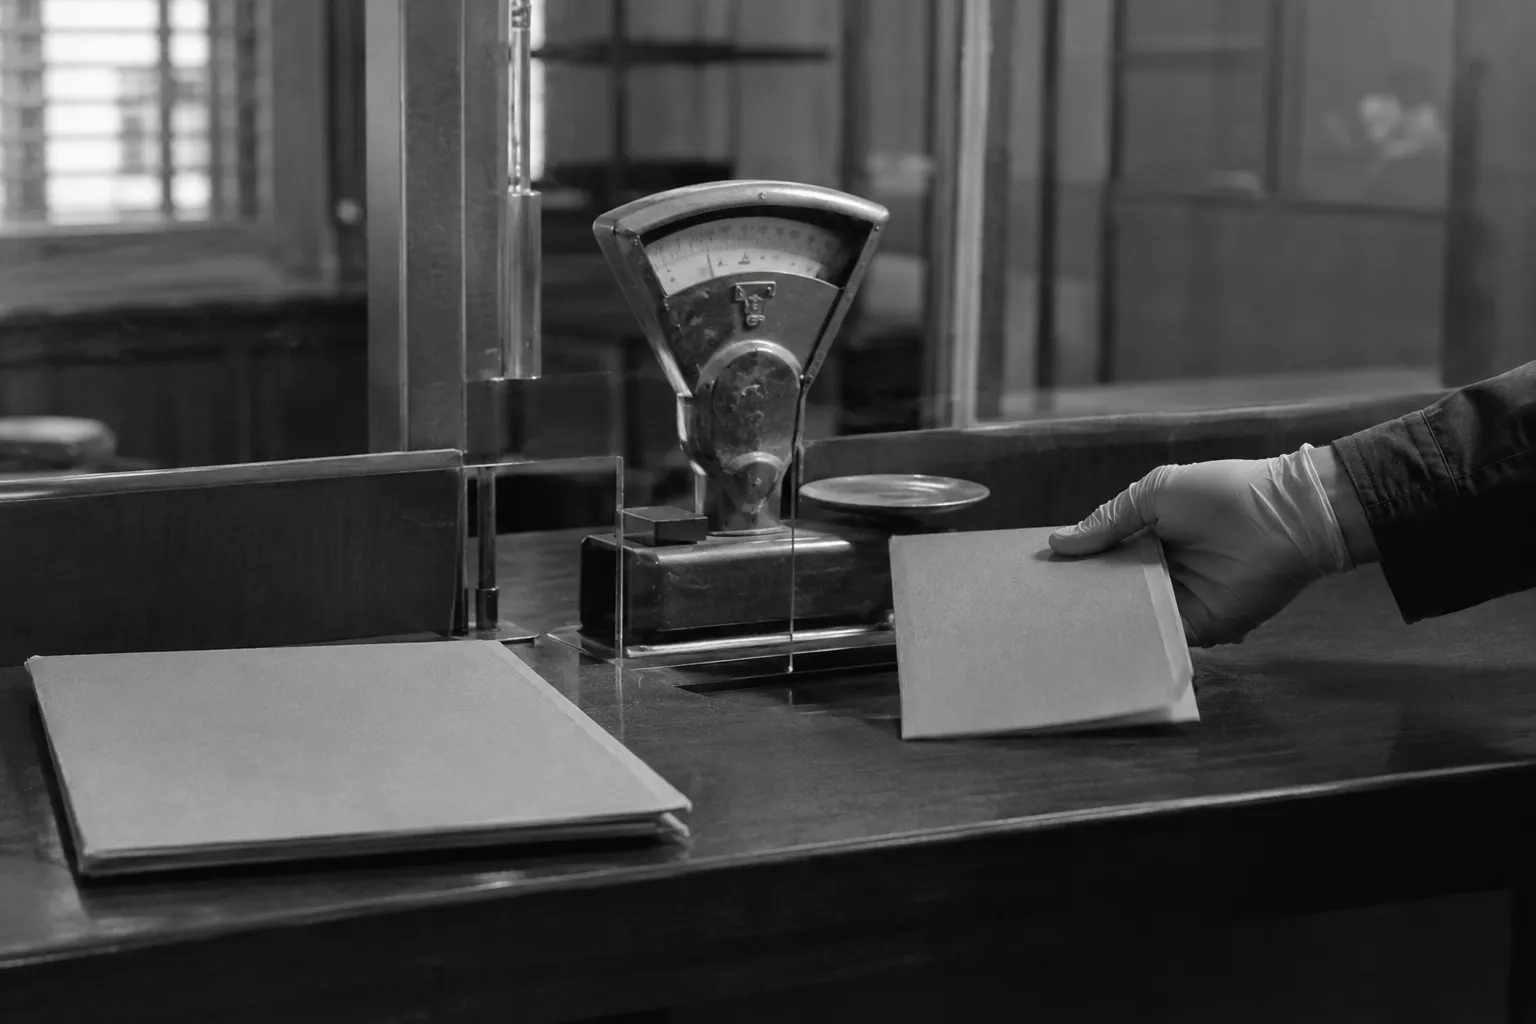
Credit scoring turns private life into a financial surface. Income, illness, employment history, address, family circumstances, and past payments can enter a system that produces a decision without showing the applicant which detail carried the most weight. A chatbot may explain a product while another model quietly decides whether the person deserves it. BaFin's intervention places a legal right beside that hidden calculation, yet transparency will remain difficult when firms rely on complex systems and outsourced vendors. The applicant still stands at the counter with a file, a request, and no view of the score. A fine can punish discrimination after it happens. It cannot easily restore the loan, insurance, or opportunity that an opaque model already refused.
El solicitante puntuado
El regulador financiero alemán BaFin empezará a supervisar cómo usan la inteligencia artificial los bancos y las aseguradoras después de que los legisladores ampliaran sus competencias, informó Reuters el 29 de julio. El organismo vigilará los chatbots de atención al cliente, los sistemas que evalúan la solvencia y las prácticas que recopilan o analizan información sensible. También podrá imponer multas cuando la IA perjudique a las personas o bloquee el acceso justo a los servicios financieros. El juicio automatizado de un banco llega ahora acompañado por un regulador encargado de revisar la maquinaria que lo produce.
La evaluación crediticia convierte la vida privada en una superficie financiera. Los ingresos, las enfermedades, el historial laboral, la dirección, las circunstancias familiares y los pagos anteriores pueden entrar en un sistema que produce una decisión sin mostrar al solicitante qué dato pesó más. Un chatbot puede explicar un producto mientras otro modelo decide en silencio si esa persona merece obtenerlo. La intervención de BaFin coloca un derecho legal junto a ese cálculo oculto, aunque la transparencia seguirá siendo difícil cuando las entidades dependan de sistemas complejos y proveedores externos. El solicitante permanece frente al mostrador con un expediente, una petición y ningún acceso a su puntuación. Una multa puede castigar la discriminación después de que ocurra. Difícilmente devuelve el préstamo, el seguro o la oportunidad que un modelo opaco ya rechazó.